Title: Financial Inclusion in the Age of FinTech and Artificial Intelligence: Evidence and Reflections from FHC 4.0
Category: Research in Brief
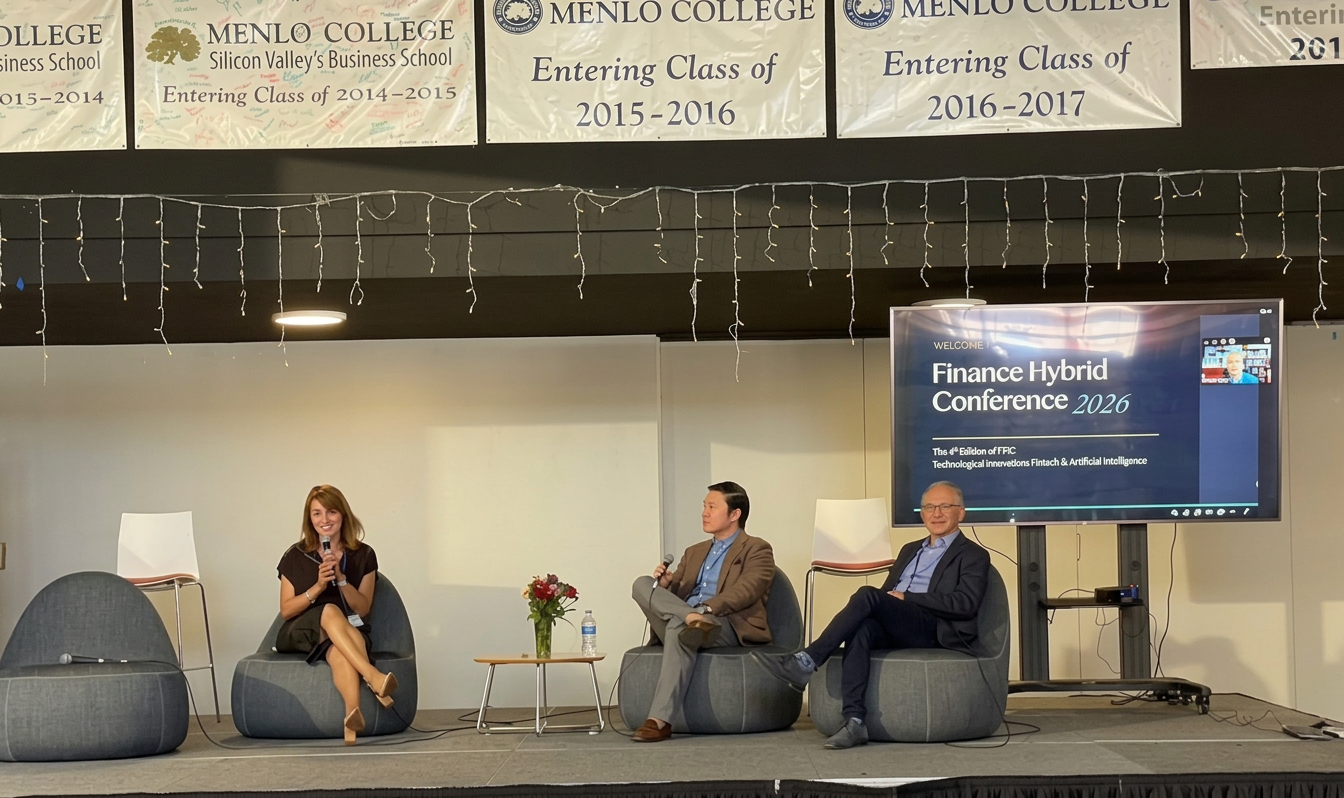
At the fourth Finance Hybrid Conference (FHC 4.0), held at Menlo College on September 25, 2026, I took part in a fireside chat with Prof. Iftekhar Hasan (Fordham University), James Wang (Creative Ventures), and Dr. Jacques Benkoski (U.S. Venture Partners). The discussion addressed two developments that are reshaping financial intermediation: the FinTech revolution and the emergence of artificial intelligence.
The promise and limits of FinTech-led inclusion
Over the past decade, neobanks and challenger banks have positioned themselves as agents of financial inclusion, promising to extend financial services to populations underserved by incumbent institutions. A central theme of our discussion was that this promise has, to date, been only partially fulfilled. Traditional banks continue to occupy a dominant position in the financial landscape. Rather than being displaced by new entrants, many incumbents have absorbed technological change, incorporating innovation and artificial intelligence solutions into their own products and services. This pattern suggests that the institutional foundations of banking (trust, scale, deposit franchises, and regulatory standing) remain decisive determinants of how financial services reach households and firms.
Empirical evidence across middle-income economies
This perspective is consistent with the findings of my recent co-authored article, “Financial Inclusion and Financial Development across Nations throughout the Economic Cycle,” accepted for publication in the International Journal of Finance & Economics on September 24, 2026.
The study examines 50 lower-middle-income and upper-middle-income countries over the period 2002–2021, using World Bank data. Financial development is measured by domestic credit to the private sector, while financial inclusion is captured by two dimensions: access, proxied by the availability of automated teller machines (ATMs), and usage, proxied by commercial bank deposits relative to GDP. Employing quantile regression, the analysis allows the effects of inclusion to vary across countries at different levels of financial development, revealing heterogeneity that conventional mean-based estimators may obscure.
The results indicate that the drivers of financial development differ systematically by income group:
- In lower-middle-income countries, growth in bank deposits exerts a strong positive effect on financial development, whereas ATM availability has a limited effect.
- In upper-middle-income countries, ATM availability plays a more important role, particularly in economies with less developed financial systems.
Policy implications
These findings caution against uniform approaches to financial inclusion. The effectiveness of inclusion strategies appears to depend on a country’s stage of financial maturity. In developing economies, priority should be given to broadening access to banking services and strengthening financial literacy. In more advanced economies, the emphasis should shift toward reinforcing financial infrastructure and regulatory frameworks.
Concluding remarks
Taken together, the fireside chat and the empirical evidence point to a common conclusion: meaningful financial inclusion remains closely tied to the depth of the formal banking system and to policies tailored to national circumstances. Technological innovation, including artificial intelligence, is most likely to advance inclusion when it complements, rather than seeks to replace, established financial institutions. Further research is needed to assess whether the rapid diffusion of AI-driven financial services will alter these dynamics in the coming years.
Reference
“Financial inclusion and financial development across nations throughout the economic cycle” ((with Elena Margarint and James Boyer). International Journal of Finance & Economics 1–16. https://doi.org/10.1002/ijfe.70315.


Leave a Reply